Blog / Orange Park Florida BMW Dealer

BMW Certified vs Used BMW Differences in Orange Park

BMW Certified vs Used BMW Differences in Orange Park

BMW Certified vs Used BMW shoppers are comparing two different pre owned paths. One carries BMW program requirements, while the other covers a broader used inventory. Therefore, the first step is knowing what the Certified label verifies. The second step is reviewing each vehicle's age, mileage, history, inspection record, and warranty status. That gives Orange Park shoppers a clearer way to compare specific vehicles without assuming one category fits everyone.

What Does BMW Certified Pre Owned Mean?

What does BMW Certified Pre Owned mean? BMW Certified means an eligible pre owned BMW completed BMW's required history review, inspection, and approval process. Eligibility comes first, so not every late model used BMW can enter the program.

BMW currently requires a Certified vehicle to be five model years old or newer. It must also have more than 300 miles and fewer than 60,000 miles. In addition, BMW requires an updated CARFAX or AutoCheck report and current maintenance history before certification.

After eligibility is confirmed, the vehicle moves through BMW's certification process. Therefore, age and mileage alone never create Certified status. BMW technicians still review the vehicle before approval.

That distinction matters when you compare local inventory. A standard used BMW may fall outside one program requirement without having a known defect. For this reason, certification status should be read as one piece of the vehicle record.

The Certified Inspection Adds a Structured Review

BMW uses a 360 degree inspection before granting Certified status. The process includes tires, wheels, brakes, body areas, mechanical components, diagnostics, and a road test. Therefore, the Certified label includes a defined manufacturer review before sale.

Why do diagnostics matter during this inspection? BMW diagnostic equipment can reveal stored faults and electronic data that a visual check cannot show. Additionally, a road test lets the technician evaluate operation while the vehicle is moving.

BMW also reviews tire and brake state before certification. Body fit and finish receive their own review as well. In addition, mechanical items must pass the required inspection steps before approval.

A standard used BMW does not automatically receive this BMW Certified process. However, that does not tell you whether the vehicle received another dealership inspection. Ask what was checked and whether service records are available.

Before choosing either path, compare the inspection record itself.

  • Ask whether the vehicle completed BMW certification or another documented inspection process.
  • Review current tire, brake, diagnostic, and service findings before deciding between two specific vehicles.
  • Request the vehicle history report so prior service, ownership, and reported events can be reviewed together.

The inspection process gives Certified shoppers a consistent manufacturer framework. Standard used shoppers should gather similar evidence from the records available for that exact vehicle.

Warranty and Roadside Support Work Differently

BMW Certified warranty coverage follows a specific sequence. The original BMW New Vehicle Limited Warranty runs for four years or 50,000 miles. After that coverage expires, the BMW Certified plan provides one year of unlimited mileage protection.

When does the Certified plan begin? It begins after the original new vehicle warranty expires. Therefore, a newer Certified vehicle may still be using original factory coverage when you purchase it.

A standard used BMW can also have remaining original factory warranty. Its age, mileage, and original in service date decide whether that coverage remains active. For this reason, shoppers should verify the exact warranty status on each vehicle.

BMW Certified vehicles also receive roadside assistance under current BMW program terms. BMW states that eligible Certified vehicles can receive roadside assistance for up to eight years. The exact term should still be verified for the vehicle under review.

Coverage details deserve careful review before purchase. Read the applicable warranty documents and ask where each coverage period begins and ends.

What a Standard Used BMW Can Offer

A standard used BMW gives shoppers access to a wider range of ages and mileage. Some vehicles may sit outside BMW Certified rules because they exceed program limits. Others may not have been submitted for certification.

Does noncertified status mean the BMW has a problem? No, that label alone does not tell you why the vehicle is outside the Certified program. Therefore, review the individual car instead of treating the category as a verdict.

Start with history and current state. Service records can show recurring maintenance and prior repair work. A vehicle history report can add ownership and reported event information. Additionally, a current inspection can show tire, brake, fluid, electrical, and mechanical findings.

A standard used BMW may also retain original factory warranty when age and mileage still qualify. In addition, dealer or third party coverage may exist on a specific vehicle. Those terms need separate verification before purchase.

Use the same evidence based process for every used vehicle.

  • Compare mileage, service records, current inspection findings, and warranty status on the exact BMW.
  • Review current tires, brakes, warning messages, fluids, and diagnostic findings before making a purchase decision.
  • Ask whether any remaining factory or other coverage applies, then review the written terms before relying on it.

This approach keeps the comparison centered on the specific vehicle instead of a broad label.

Which Pre Owned BMW Path Fits Your Search?

Which pre owned BMW path fits your search? Compare age, mileage, inspection status, warranty status, history, and current inventory before choosing. Those factors give you a clearer basis than the Certified badge alone.

Start by deciding how narrow your search should be. BMW Certified inventory follows BMW age, mileage, history, and inspection rules. Standard used inventory can include vehicles outside those program limits. Therefore, the standard used pool may offer more model years, mileage ranges, and price points.

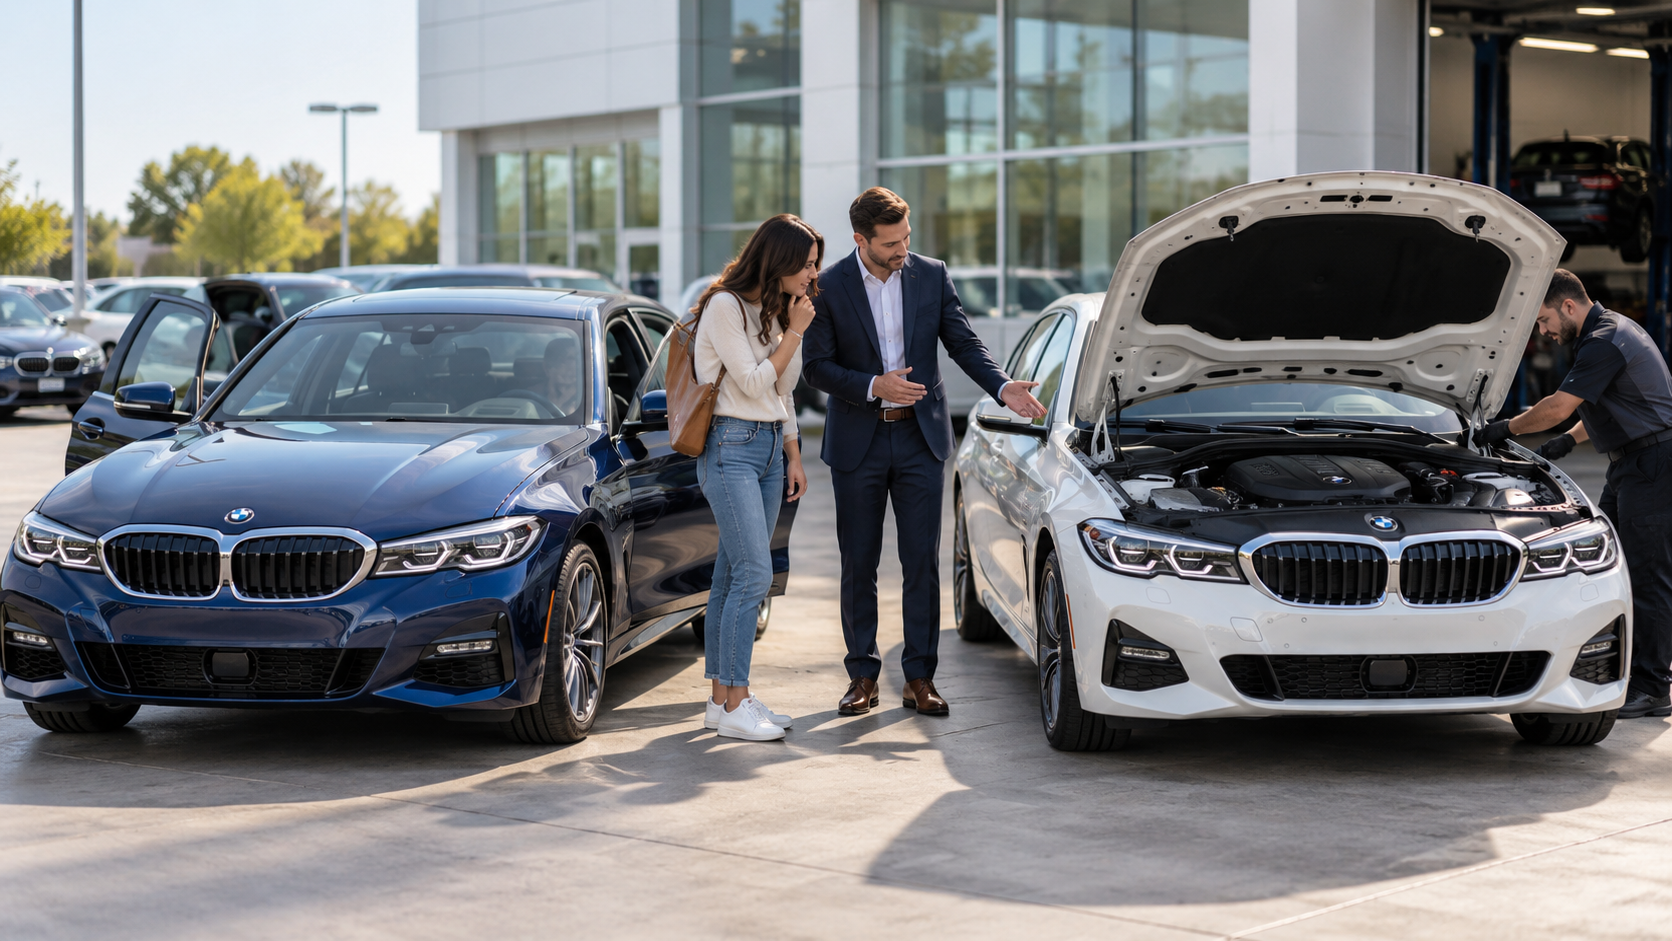
Next, compare two actual vehicles side by side. Review their service records, inspection details, warranty status, mileage, equipment, and current asking price. Additionally, drive both vehicles when possible so you can check seating, controls, ride quality, braking, and visibility.

Tom Bush BMW Orange Park currently offers both BMW Certified and broader pre owned inventory. The dealership also provides finance and trade appraisal paths for shoppers moving beyond research.

A Certified BMW gives you a manufacturer defined eligibility and inspection process. A standard used BMW gives you a broader set of vehicles to evaluate individually. Review the records, inspect the exact car, and verify coverage before choosing the path that fits your search.
Posted in:

Related Posts

First time BMW

First Time BMW Guide for Choosing Your First Model

First time BMW research gets easier when you sort body style, drivetrain, energy source, and purchase path in that order. However, BMW names can look dense when several letters and numbers appear together. Therefore, a clear sequence keeps the lineup easier to read. First, start with the vehicle shape that fits your passengers and cargo. Then look at drivetrain and fuel type. In addition, compare new, Certified, and standard used choices after that. Finally, review lease, finance, warranty, and service details before a test drive. Reading BMW Model Names What do BMW letters and numbers tell you? They give clues about model family, body type, drivetrain, and electrification. Therefore, numbered Series identify core car families such as the 3 Series and 5 Series. In addition, X models identify BMW SUVs and Coupe SUVs. M names point toward BMW M models, while an i prefix identifies a battery electric model. An e suffix can identify a plug in hybrid configuration. Therefore, a name such as X5 xDrive50e gives several clues before you open the specification page. X5 names the SUV family, xDrive identifies all wheel drive, and the e suffix points to plug in hybrid power. You do not need to memorize every badge. Instead, learn the pieces that narrow the lineup first. more Series and X names tell you which vehicle family you are viewing. xDrive identifies all wheel drive, while some sDrive models use rear wheel drive. An i prefix points to battery electric power, while an e suffix can mark a plug in hybrid. Beyond that, trim details can wait until the body style and drivetrain fit your plans. This keeps early research focused on the choices that change the vehicle most. Choose the Body Style Before the Trim Which BMW shape fits your passenger and cargo needs? The answer starts with how you expect to carry people and gear. Sedans such as the 3 Series and 5 Series use a separate trunk and four door cabin. Coupes place more emphasis on a lower roofline and two door form. Gran Coupe models keep coupe inspired lines while adding four doors and a rear hatch on certain models. In addition, BMW X models add taller seating and easier cargo access through a rear liftgate. Larger X models also offer more cabin room than smaller entries in the same family. Touring models use a wagon shape with a longer roof and rear cargo opening. Body Style Comparison BMW Body Style Passenger Access Cargo Layout Good Fit When Sedan Four doors Separate trunk You want a lower car with simple rear access Coupe Two doors Separate trunk You prioritize two door styling and front seat access Gran Coupe Four doors Varies by model You want coupe inspired lines with easier rear entry X model Four doors Rear liftgate You carry taller cargo or want a higher seating position Touring Four doors Long roof cargo area You want car height with more rear cargo room For this reason, body style can remove several models from your list quickly. A family carrying strollers may start with an X model or Touring model. A commuter who values a smaller footprint may begin with a sedan. Rear Wheel Drive and xDrive Change the Drivetrain Choice What does xDrive change? xDrive sends power through an all wheel drive layout instead of sending power only to the rear wheels. BMW uses xDrive across cars and X models. Therefore, the name tells you something mechanical, not simply an equipment package. The drivetrain can send power to more than one axle as traction needs change. By contrast, rear wheel drive sends propulsion through the rear axle. In addition, this layout remains available on selected BMW models and can reduce drivetrain weight. It also gives the front wheels fewer propulsion duties. For Orange Park and Jacksonville driving, road surface and personal preference should guide the comparison. Heavy rain may make all wheel drive attractive to some shoppers. Still, tires remain central to grip on wet pavement. During a test drive, compare steering response, acceleration from a stop, and low speed maneuvering. Those details show how each drivetrain feels on the routes you travel most. Gasoline Plug In Hybrid and Electric BMW Models Which energy source fits your commute? BMW currently offers gasoline, plug in hybrid, and battery electric choices. Therefore, gasoline models rely on an internal combustion engine and fuel tank. Refueling follows the familiar gas station routine. Plug in hybrid models add a high voltage battery and electric motor while keeping a gasoline engine. That plug in hybrid setup can cover shorter trips with electric power when the battery has charge. However, the gasoline engine remains available for longer travel. Home charging becomes part of the routine if you want to use more electric miles. Battery electric BMW models remove the gasoline engine. Instead, the high voltage battery powers one or more electric motors. Charging access at home, work, or public stations becomes a larger part of trip planning. Before choosing among these paths, compare your normal mileage and parking setup. In addition, think about how frequently you take longer trips beyond your local route. A shopper with reliable home charging may view an electric model differently from someone without dedicated parking. New BMW Certified and Used Paths What changes between new, BMW Certified, and standard used inventory? Each path carries a different mix of age, mileage, inspection, warranty timing, and price. A new BMW begins with the current model equipment and a new vehicle warranty. BMW states that its New Vehicle Limited Warranty runs four years or 50,000 miles. Therefore, the warranty clock starts with the original in service date. BMW Certified inventory follows a separate qualification process. Current BMW rules limit qualifying vehicles to five years old or newer with fewer than 60,000 miles. In addition, the vehicle must pass history review, inspection, diagnostic checks, and road testing. By contrast, standard used inventory can include a wider range of ages and mileage. Therefore, service records, condition, prior repairs, and an inspection deserve close review. Inventory Path Comparison Path Main Starting Point Warranty Review What to Check Closely New BMW Current model and zero prior owner miles New vehicle coverage Equipment, payment path, service plan BMW Certified BMW qualification and inspection Remaining new coverage plus CPO term when eligible In service date, mileage, history Standard used BMW Broader age and mileage range Varies by vehicle Records, condition, prior repairs, inspection For this reason, BMW Certified should not be treated as another label for used inventory. The certification process adds BMW rules before the vehicle enters that category. Lease Finance Warranty and Service Basics What should you review before committing to your first BMW? Review payment structure, warranty dates, maintenance coverage, insurance, and service access. A lease sets a term, mileage allowance, and end of term choices. Therefore, expected annual mileage deserves attention before signing. Financing uses a loan structure and can lead to full ownership after the balance is paid. BMW warranty coverage should be reviewed separately from the payment choice. Current new BMW models also include factory scheduled maintenance through BMW Ultimate Care. Review the stated time and mileage window. In addition, service planning deserves a place in the first purchase conversation. Tom Bush BMW Orange Park provides BMW service, parts, and scheduling resources after delivery. For this reason, review service location and scheduling options before you need them. Before the test drive ends, compare these final items in person: Adjust the driver seat, rear seat, mirrors, and cargo area to match the way you travel. Review the exact drivetrain and energy source on the model you are driving. Ask for the warranty start date, maintenance terms, and payment details tied to that specific vehicle. Your first BMW choice should get narrower as each decision falls into place. Start with body style, then drivetrain, energy source, and inventory path. After that, compare payment and service details on the exact vehicle you plan to drive.

BMW 3 Series Lease vs Finance

BMW 3 Series lease vs finance comparisons usually begin with monthly payments, but the larger difference comes from how each option handles depreciation, ownership, mileage, and long-term vehicle cost. Both financing and leasing create very different ownership structures even when the same BMW sedan is involved. One path prioritizes lower short-term payments and shorter ownership cycles. The other builds equity while extending ownership length beyond the factory warranty window. Understanding how these structures work helps shoppers evaluate which option fits their driving habits, commuting distance, technology priorities, and long-term financial plans more naturally. Why BMW 3 Series Lease Payments Usually Cost Less Per Month BMW lease payments are usually lower because the lease contract only finances the portion of the vehicle expected to depreciate during the lease term. Instead of paying toward the entire vehicle value, the customer pays for projected depreciation plus interest and fees during the lease window. Residual value plays a major role in this structure. Residual value is the projected worth of the BMW 3 Series at the end of the lease term. Since BMW sedans maintain relatively strong projected resale positioning, the amount financed during the lease can remain smaller than a traditional purchase loan. A finance contract works differently. Financing covers the full negotiated vehicle price along with taxes, fees, and interest across the loan term. Because the entire vehicle value becomes financed, monthly payments usually rise higher than lease payments for the same BMW model. BMW lease structures commonly include: more • Lower monthly payments • Shorter ownership cycles • Residual value forecasting • Mileage agreements • Lease-end inspection requirements • Optional buyout opportunities This creates strong appeal for drivers who prefer upgrading vehicles more frequently or prioritizing lower monthly obligations over long-term ownership accumulation. Mileage and Driving Habits Matter More During Leasing Mileage restrictions exist because lease contracts are built around projected vehicle resale value. The more miles accumulated during the lease term, the lower the vehicle value becomes at lease maturity. BMW Financial Services calculates lease structures partially through expected future resale positioning. If mileage rises substantially beyond contract limits, the residual projection changes and the vehicle may return worth less than originally forecasted. This matters heavily for commuters and long-distance drivers. Someone driving twenty thousand miles annually may encounter much different lease economics than someone commuting locally with limited annual mileage accumulation. Driving routines that influence lease evaluation include: • Long interstate commuting • Frequent road travel • Urban stop and go driving • Business travel mileage • Weekend recreational driving • Multi-driver household usage Wear assessment also becomes part of the lease-end process. Excess wheel damage, interior wear, tire wear, windshield damage, or body panel damage can trigger additional charges depending on lease return condition. Financing eliminates mileage restrictions entirely because ownership transfers directly to the buyer. The owner absorbs depreciation naturally through vehicle aging instead of operating within a predefined residual structure. This creates more flexibility for drivers whose commuting habits fluctuate unpredictably throughout ownership. Financing Builds Equity Through Principal Reduction Financing changes ownership math because each monthly payment gradually reduces the loan principal balance. As the remaining loan amount decreases, ownership equity begins building inside the vehicle. Equity becomes important when trade-in timing changes later. If the BMW 3 Series maintains stronger resale positioning than the remaining loan balance, the owner may carry positive equity into the next transaction. That equity can reduce the balance of the next vehicle purchase or lower future monthly payments. Loan amortization determines how equity builds. Early loan payments apply more heavily toward interest, while later payments reduce principal balance more aggressively. Factors influencing financing structure include: • Loan term length • Interest rate structure • Down payment amount • Vehicle depreciation timing • Annual mileage accumulation • Trade-in timing Longer loan terms lower monthly payments but slow equity progression because interest remains distributed across a larger time window. Shorter loans raise monthly obligations but reduce interest accumulation and build ownership position faster. Technology cycles also influence financing evaluation. BMW interiors, driver assistance features, infotainment systems, and connectivity platforms evolve quickly. Buyers financing for extended ownership periods should evaluate how long they intend to keep the vehicle before newer technology shifts begin influencing satisfaction later. Warranty Timing Changes Lease and Finance Ownership Exposure BMW factory warranty timing shapes lease and finance decisions substantially because repair exposure changes after factory coverage expires. Most BMW lease terms overlap heavily with factory warranty protection, which reduces exposure to major repair expenses during the lease cycle. This creates predictability for many lessees because maintenance concerns and unexpected repair exposure remain limited during the ownership period. Drivers return the vehicle before aging electronics, suspension wear, cooling system failures, or high mileage repair exposure becomes more likely. Financing extends ownership much longer in many cases. Once factory coverage expires, the owner becomes responsible for repairs involving electronics modules, suspension components, cooling systems, drivetrain repairs, and sensor calibration issues. Ownership timing influences: • Repair exposure • Maintenance planning • Tire replacement cycles • Brake replacement timing • Electronics aging • Long-term operating costs Someone financing a BMW 3 Series for seven years may encounter very different maintenance exposure than someone leasing for three years and returning the sedan before higher mileage accumulation occurs. This does not automatically make leasing financially superior. Financing can still create lower overall long-term vehicle cost if the owner keeps the sedan substantially beyond loan payoff and maintains the vehicle carefully after the payment cycle ends. What Happens at the End of a BMW Lease or Loan The ownership path changes substantially once the agreement reaches maturity. At the end of a BMW lease, the customer usually has several available paths including returning the vehicle, purchasing it through a lease buyout, or transitioning into another BMW lease or finance agreement. Before return, the dealership or lease company evaluates mileage accumulation, vehicle condition, tire wear, cosmetic damage, and overall lease compliance. Excessive wear or over-mileage charges may apply depending on contract terms. Lease-end options commonly include: • Returning the vehicle • Purchasing the leased BMW • Starting another lease • Financing a replacement vehicle • Trading the vehicle early in some cases Financing works differently because the vehicle becomes fully owned after the loan balance reaches zero. Once paid off, the owner can continue driving without monthly payments, sell the vehicle privately, trade it toward another purchase, or refinance remaining balance if necessary earlier in the loan cycle. BMW 3 Series lease vs finance decisions therefore extend far beyond monthly payment differences alone. Mileage patterns, ownership length, warranty timing, repair exposure, technology preferences, and long-term financial goals all shape which structure feels more natural for different drivers.

What Out the Door Price Means at a BMW Dealer

Out the door price meaning becomes much clearer once buyers understand how taxes, registration, financing structure, dealership fees, and optional products combine into the final purchase agreement total. Many vehicle shoppers first encounter pricing confusion after seeing an advertised BMW price online, then noticing the final transaction amount changes during the purchase process. That difference does not automatically come from hidden pricing. Vehicle transactions contain multiple pricing layers that extend beyond MSRP alone. Understanding how those components work together helps buyers review dealership paperwork with greater clarity before signing final purchase documents. MSRP Is Only One Part of Final Vehicle Pricing MSRP represents the manufacturer's suggested retail price before taxes, registration, state fees, financing, and dealership processing costs are applied. Advertised pricing usually reflects the vehicle itself rather than the completed transaction structure. Once a buyer moves forward with a purchase, additional costs begin layering into the agreement. State sales tax calculations apply based on local tax law. Registration and title processing charges are added through state motor vehicle agencies. Dealership documentation fees cover contract preparation, filing procedures, title transfer processing, and transaction administration. These categories create the out the door total buyers see before finalizing paperwork. The final transaction amount commonly includes: more • Vehicle sale price • State sales tax • Title processing fees • Registration charges • Documentation fees • Trade in balance adjustments • Optional protection products A BMW purchase agreement therefore functions more like a complete transaction summary than a simple vehicle price sheet. This explains why two buyers purchasing similarly equipped vehicles may still receive different out the door totals depending on registration location, trade in structure, financing setup, and optional product selection. Financing Structure Changes More Than Monthly Payments Many buyers focus heavily on monthly payment figures during financing conversations, though loan structure changes the total transaction cost much more broadly than the payment amount alone. Loan term length, interest rate, down payment amount, and financed balance all influence the final amount paid throughout the loan. A lower monthly payment may still increase total interest paid if the financing term extends substantially longer. BMW financing structures also change depending on whether optional protection plans, maintenance coverage, wheel protection, or service contracts are added into the financed balance. Once those products become financed inside the loan, interest applies across those costs as well. Financing calculations usually include: • Loan principal balance • Interest rate structure • Loan term length • Down payment amount • Trade in equity application • Optional financed products • Remaining balance after taxes and fees This creates situations where two buyers can purchase identical BMW models yet carry dramatically different total ownership costs based on financing structure alone. Understanding the relationship between financed balance and total repayment amount gives buyers a clearer picture of the transaction beyond the monthly payment figure shown during negotiations. Trade Ins and Optional Products Reshape Final Pricing Trade ins influence dealership pricing in several different ways. Vehicle equity can reduce the financed balance directly, while negative equity from an existing loan can increase the new transaction amount if unpaid balance remains after the trade valuation is applied. Some states also apply sales tax differently when trade in value offsets the taxable vehicle amount. That adjustment can alter total taxes due during the transaction depending on local regulations. Optional products create another major pricing shift. Wheel and tire coverage, prepaid maintenance plans, GAP protection, service contracts, appearance protection, and theft recovery products all increase the final agreement total if selected during financing. These additions change: • Financed balance size • Monthly payment amount • Loan interest accumulation • Total repayment amount • Contract structure complexity This is one reason buyers reviewing only monthly payment numbers may overlook how optional products alter the overall financial structure of the transaction. Understanding how each product changes the financed balance helps buyers evaluate whether the added coverage matches their priorities before completing paperwork. Purchase Agreements Break Down Pricing Step by Step BMW dealership purchase agreements separate pricing into individual categories so buyers can review how the final transaction total is constructed. The agreement is designed to show where each amount originates rather than presenting one unexplained number at the end of the process. The paperwork generally begins with the vehicle sale price, then applies taxes, registration, fees, trade in adjustments, financing calculations, and optional products sequentially. Dealership documentation fees are commonly misunderstood because buyers sometimes interpret them as arbitrary charges. In reality, documentation processing covers administrative preparation tied to registration filing, lender coordination, contract handling, title processing, compliance paperwork, and transaction record management. The agreement structure usually separates: • Vehicle pricing • Tax calculations • Registration and title charges • Dealer processing fees • Trade in balance adjustments • Optional product selections • Financing calculations Reviewing the transaction line by line creates a much clearer understanding of how the out the door amount was assembled. That process also gives buyers an opportunity to ask questions before signing rather than reviewing totals only after financing has already been finalized. What Buyers Should Review Before Signing Final BMW Paperwork Vehicle transactions move quickly once financing paperwork begins, which makes preparation extremely important before arriving at the dealership. Buyers should review the full pricing structure carefully and understand how each category contributes to the final transaction amount. Questions worth reviewing include whether taxes were calculated correctly, whether trade in payoff balances match lender statements, whether optional products were intentionally selected, and whether financing terms align with the agreed structure. Before signing, buyers should review: • Final sale price • Tax calculations • Registration charges • Documentation fees • Loan interest rate • Loan term length • Trade in payoff balance • Optional product selections • Monthly payment structure • Total financed amount Out the door pricing exists to show the completed transaction total after every financial layer has been applied. Understanding how those categories work together helps BMW buyers move through the purchase process with stronger clarity and greater confidence before finalizing paperwork.